In every dysfunctional family system, there is a designated load-bearing wall. For as long as my memory serves, that wall was me.
My name is Mark. At thirty-two years old, I had spent the better part of a decade operating under the quiet, exhausting illusion that being dependable was synonymous with being loved. I lived alone in Denver, working as a senior systems administrator—a career built entirely on diagnosing systemic failures, isolating broken dependencies, and restoring equilibrium to chaotic networks. My apartment was clean, spare, and deliberate. I drove a reliable sedan, avoided ostentatious spending, and saved diligently. I was neither wealthy nor impoverished, but I possessed what my family viewed as an inexhaustible commodity: financial margin.
In my family’s collective mythology, financial margin was not the product of eighty-hour workweeks, deferred gratification, or disciplined budgeting. It was treated as an unearned windfall, a surplus hoard that rightfully belonged to the collective.
My mother, Karen, was an artist of passive-aggressive domesticity whose primary currency was manufactured crisis. My father, Jeff, was a former middle manager whose chronic financial illiteracy was matched only by an unyielding, fragile patriarch’s pride. Together, they had spent thirty years living precisely three steps ahead of financial ruin, using cosmetic renovations and manicured suburban appearances to mask an empty treasury.
Flanking them were my adult siblings. Rachel, twenty-eight, was a chaotic mother of three who drifted through low-wage administrative jobs and tumultuous romances, forever convinced that her life’s friction was an injustice inflicted by the universe rather than the inevitable consequence of her total refusal to plan. Eric, twenty-six, was an evangelist of perpetual entrepreneurship—always thirty days away from securing seed funding for apps that never launched, surviving on credit extensions and parental bailouts.
For years, the script never varied. If Rachel’s car threw a rod, Mark paid the mechanic. If my father’s intermittent contracting gigs dried up between corporate budget cycles, Mark floated the mortgage supplement. When my father underwent gallbladder surgery two years prior and wept over the kitchen table about the indignity of choosing between blood pressure medication and groceries, I had handed him an authorized-user card on one of my primary lines of credit.
“Use it for the prescriptions, Dad,” I had instructed gently, sitting beside him in their cluttered kitchen. “Groceries and medicine until you get your feet back under you.”
“You’re a good son, Mark,” he had whispered, his voice trembling with an emotional cadence I mistook for genuine gratitude. “A real safety net. I don’t know what we’d do without you.”
I had forgotten to revoke that card. When his surgical incisions healed and he returned to work, the card slipped into the dark recess of administrative neglect. I trusted him. In the transactional economy of our family, I thought my compliance had bought peace.
Thanksgiving at my parents’ house was always an exercise in psychological endurance. We gathered beneath the low ceilings of their split-level home in the suburbs, the atmosphere heavy with the dry, unmistakable scent of overcooked turkey, canned green beans, and unspoken grievances.
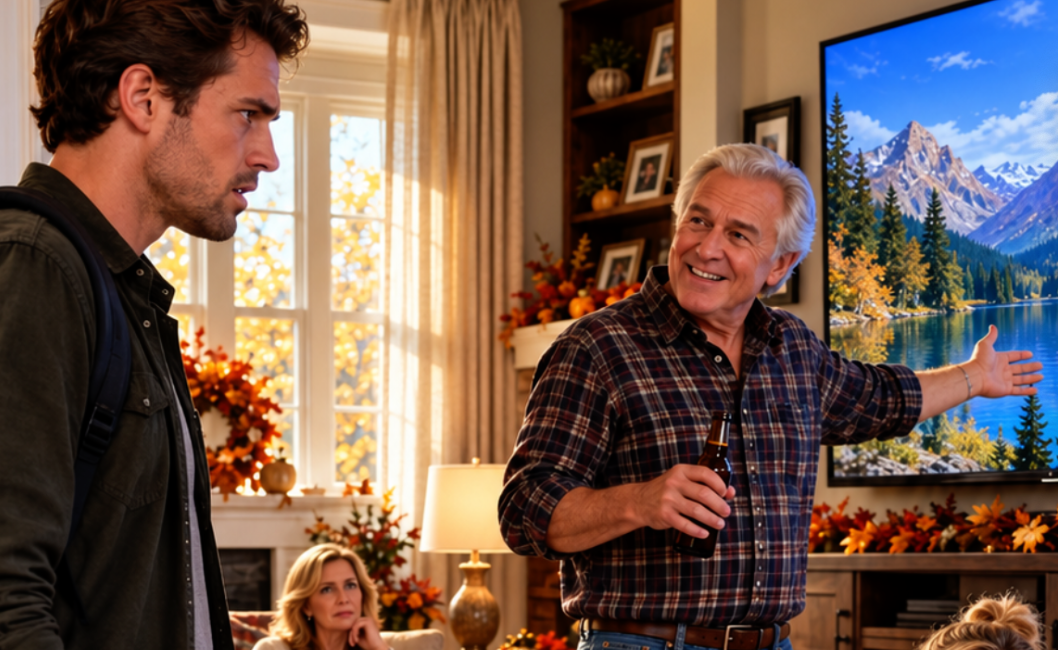
When I stepped through the front door that Thursday afternoon, the living room had been radically transformed. Gone was the threadbare, sagging floral sofa from my adolescence. In its place sat a sprawling, modular sectional in slate-gray performance fabric, anchored by an expansive wool-blend rug and flanked by motorized blackout draperies. Dominating the far wall was a seventy-two-inch ultra-high-definition television, its glossy screen humming with the pristine, saturated motion of a holiday football broadcast.
Rachel was curled into the chaise lounge, tapping furiously on her phone while her three children scrambled across the pristine upholstery with juice boxes in hand.
“Look at this place,” she announced the moment I walked in, gesturing grandly with her elbow as if she had personally commissioned an interior designer. “Finally got rid of that depressing seventies junk. Feels like a real home now.”
My mother emerged from the kitchen carrying a ceramic bowl of instant stuffing, her face flushed with pious satisfaction. “God provides, Mark,” she said, her voice dropping into the breathy, sanctimonious timbre she reserved for church socials. “We’ve just been so abundantly blessed this season.”
My father stood near the hearth, leaning against the mantle with an open beer. He caught my eye and offered a broad, easy grin, completely devoid of sheepishness.
I stood in the entryway, my coat still folded over my arm, feeling an acute, jarring sense of cognitive dissonance. My father had retired on a meager corporate pension fifteen months prior; my mother’s occasional substitute teaching barely covered their monthly pharmaceutical out-of-pocket costs. Yet, here sat at least six thousand dollars of pristine consumer merchandise, accompanied by the distinct smell of newly unpacked polyurethane and factory foam.
“Must have been quite a year for the investments, Dad,” I murmured quietly, keeping my voice neutral as I hung my coat in the hall closet.
“We make do, son,” he said, turning his attention back to the screen. “You know how it is. Family comes together. Things work out.”
The dinner was brief and brittle. Rachel spent forty minutes detailing why her children’s school district was failing to accommodate their individual geniuses, Eric dominated the turkey carving with a convoluted pitch for a peer-to-peer peer-lending platform, and my parents nodded along, beaming at their progeny like proud patrons of the arts. As was my custom, I excused myself early, citing a server deployment scheduled for 6:00 AM the following morning.
I drove home through the frigid Colorado darkness, a low, persistent hum of unease vibrating in the back of my skull. It was not suspicion yet—merely that primal intuition that surfaces when numbers in a ledger fail to balance.
The truth arrived not with a cataclysmic confrontation, but on a quiet Sunday evening beneath the hum of a desk lamp.
I was sitting in my armchair with a cup of black coffee, running through my end-of-month reconciliations. As I scrolled through my primary credit account, an unrecognized line item halted my thumb:
I clicked into the transaction details. The charge had cleared two days before Thanksgiving.
My first thought was typical of an IT professional: a card compromise, a cloned credential, or a data breach. I immediately dialed the merchant services number listed on the merchant statement.
“Interior Comforts, this is Brenda,” a cheerful voice answered over a background of soft retail jazz.
“Hi Brenda,” I said, my tone clipped and professional. “I’m looking at a charge on my statement from November twenty-fourth for twenty-three hundred and forty-two dollars. I didn’t authorize this purchase. Can you tell me what order this was associated with?”
There was a moment of rhythmic typing. “Yes, Mr. Miller. That was an in-store order placed on the twenty-second. We have a delivery receipt signed on the twenty-fourth. It includes the six-piece modular sectional in charcoal, the custom drape package, a twin-over-full bunk bed set with matching mattresses, and premium delivery installation.”
The air left my chest in one cold, sickening rush. “Who signed the delivery invoice?”
“Signed by Jeffrey Miller. Delivery address is Forty-Two Maple Crest Drive.”
“Thank you, Brenda.”
I hung up the phone. I sat motionless in the stillness of my apartment for several long minutes, listening to the radiator clink against the floorboards. Forty-Two Maple Crest Drive was my childhood home. The card used was the legacy credit line where my father remained an authorized user.
I did not call ahead. I grabbed my keys, stepped into the biting November chill, and drove the forty minutes back to the suburbs.
When I pushed open the unlocked front door of my parents’ home, the scene was nearly identical to Thanksgiving. The television was blaring; Rachel was on speakerphone in the kitchen, arguing with an ex-partner; and my father was seated in the middle of the sectional, remote in hand.
The bunk bed set Brenda mentioned was not in the living room; it had undoubtedly been assembled in Rachel’s old bedroom down the hall for her boys.
My father turned his head as the door clicked shut. His expression didn’t shift into guilt. He did not freeze. Instead, he smiled—that same patronizing, folksy grin he had worn three days prior.
“Hey, there he is!” he called out, waving the television remote toward the new leather ottoman. “Didn’t expect you back so soon. Nice, right? Sit down, try it out. Beats that old sawdust couch we had, doesn’t it?”
I remained standing in the threshold, my boots planted on the linoleum. “You charged twenty-three hundred dollars to my account, Dad.”
Rachel paused her phone call in the kitchen, peering through the entryway arch with an immediate sneer. My mother walked out from the hallway, drying her hands on a dishtowel, her expression instantly defensive.
“Oh, don’t start with that tone, Mark,” my father said, waving his hand dismissively as if brushing away a housefly. “We needed to update the place. Rachel’s kids needed actual beds that don’t sag to the floorboards. We figured, look, you’re single. You don’t have children. You don’t have a family to support. You’re pulling down corporate tech money in the city. It’s only right that you pitch in for the family that does.”
Rachel crossed her arms, leaning her hip against the drywall. “Seriously, Mark. Don’t be so dramatic. It’s not that deep. It’s just a little help. You can write it off or pay it down in a month anyway.”
I looked from my sister’s defiant posture to my father’s calm, unblinking eyes, and finally to my mother, who simply nodded in solemn agreement with her husband. There was no apology waiting to be coaxed out. There was no shame. There was only an absolute, terrifying sense of communal ownership over my life and my labor.
I didn’t scream. I didn’t slam a fist into the drywall.
Instead, a single, sharp laugh escaped my throat—dry, clinical, and completely empty of humor.
“Cool,” I said softly, my voice barely carrying above the television volume. “Then you’re really going to love what comes next.”
Rachel rolled her eyes and turned back to her phone. “Whatever, Mark. Go be miserable somewhere else.”
I walked out the door, closed it gently behind me, and drove back to Denver.
When I returned to my desk that night, the emotional haze had dissolved, replaced by the precise, hyper-focused detachment I used when auditing an infected enterprise infrastructure.
I pulled up my full credit reports from Experian, Equifax, and TransUnion. I pulled five years of banking archives, merchant statements, and institutional loan files. What had begun as an unauthorized charge for a living room suite rapidly unfurled into a sprawling, multi-year parasite embedded deep within my financial identity.
The furniture was merely the latest extraction.
Fourteen months prior, a secondary unsecured signature loan of six thousand dollars had been originated through a regional credit union using my identity and household income metrics. The funds had been deposited directly into my father’s checking account. I remembered the event now with sickening clarity: a Sunday dinner where my father had shoved a stack of refinancing papers across the kitchen island, claiming it was an affidavit removing an old lien from his truck. “Just initial here and sign the back, Mark. Standard bureaucratic garbage.”
I found an open line of revolving credit at a national hardware chain, opened three years prior under my Social Security number with my mother listed as an authorized purchaser. The current balance: $4,120.
I discovered that during their last mortgage restructuring, they had listed me not merely as a family reference, but as an active financial co-guarantor—leveraging my pristine 810 credit score and tech salary to secure a prime interest rate they had no legal or financial right to command.
Then came the recurring charges.
Buried in a secondary checking account I had kept open from my college years were twenty-four months of continuous automated clearinghouse withdrawals. My accounts had been paying their high-speed internet package, their municipal water and sanitation bills, their natural gas line, and an assortment of streaming services and subscription accounts utilized exclusively by Rachel and Eric.
They had turned me into a living utility company, an unpaid guarantor, and a private line of credit—all while treating me like an emotionless ATM whose sole function was to absorb the consequences of their irresponsibility.
I opened an administrative text editor and drafted a systematic, non-negotiable remediation protocol.
At 1:15 AM, I logged into my credit card dashboard, revoked my father’s authorized user credentials, and reported the card stolen to prevent any pending transactions from executing.
At 1:45 AM, I contacted the fraud departments of all three major credit bureaus, placing an immediate, hard security freeze on my credit files. No new lines could be queried, opened, or modified without a multi-factor pin sent exclusively to my hardware security key.
At 2:30 AM, I systematically navigated to the billing portals for the regional energy provider, the municipal water district, and the telecom provider. Because the online profiles were anchored to my original contact email, I initiated password resets, removed my checking and routing numbers from the automated billing engines, and permanently deleted the recurring payment profiles.
At 3:15 AM, I filed an official digital identity fraud report with the Federal Trade Commission and drafted formal dispute letters to the credit union and the home improvement retailer.
I shut the lid of my laptop. The silence in my apartment was profound. For the first time in my adult life, I felt the cold, bracing purity of zero complicity.
The algorithmic dominoes did not take long to fall.
When Monday morning arrived, the municipal utilities and corporate servers executed their automated batch processing. Without my credit line to absorb the recurring debts, and with the mortgage payment bouncing against a drained, un-subsidized joint checking account, the system began its ruthless mechanical work.
My phone remained face-down on my desk throughout my morning standup meetings. By noon, the device was vibrating almost continuously against the mahogany surface.
Seventy-four missed calls.
Forty-two text messages.
The tone of the messages tracked the classic stages of narcissistic collapse:
Then, at 12:45 PM, a multimedia message arrived from an unknown VoIP number.
It was a photograph of a neon-orange legal document affixed to the peeling paint of my parents’ front door with heavy-duty masking tape.
I stared at the image. The mortgage had not simply lapsed because of this month’s payment. They had been skating on grace periods and deferred delinquency schedules for the better part of a year, relying on my occasional automated transfers to keep the lender from initiating structural proceedings. By pulling my name and freezing the co-guarantor authorization, the lender’s risk algorithms had immediately re-assessed the loan, discovered the fraudulent income certifications, and moved the asset directly into the foreclosure pipeline.
My chest did not tighten. My pulse did not race.
I hired an attorney specializing in consumer fraud and estate litigation by 2:00 PM.
His name was David Vance, a pragmatic, silver-haired practitioner who listened to my chronological narrative without interrupting once. When I finished placing the file folders, loan numbers, and forged affidavits on his mahogany conference table, he leaned back in his leather chair and let out a low whistle.
“You realize what happens if we push these fraud affidavits through to the state attorney and the primary lenders?” Vance asked, peering over his reading glasses. “This isn’t a civil dispute over Thanksgiving dinner, Mark. Your father forged your signature on an institutional financial instrument. That is a class-four felony. The car refinancing, the furniture financing, the signature loan—if the bank’s forensic team reviews this, they won’t just foreclose on the house. They can refer this for criminal prosecution.”
I looked out the conference room window toward the snow-dusted peaks of the Front Range.
“Mr. Vance,” I said evenly, “I spent twelve years carrying their debt because I thought family meant protecting people from consequences. All I did was finance their delusion. Serve the papers.”
When direct intimidation fails, an abusive family system immediately deploys its peripheral network: the flying monkeys.
On Wednesday, my phone—still active on its original number while I finalized my transition to a new carrier—lit up with calls from extended relatives I had not spoken to since my high school graduation.
My cousin Ashley called first. Ashley, who only ever reached out when she needed airport transportation or a temporary loan for an apartment deposit, left a breathless, weeping voicemail: “Mark, please, your mom is beside herself. She’s having chest pains. You can’t let them lose the house over some misunderstanding about furniture. You have so much, and they have so little. Where is your heart?”
Next came Aunt Mara, my mother’s older sister, whose specialty was weaponized religious guilt. She sent a five-hundred-word text message detailing how God detests an unforgiving spirit, reminding me that my parents had clothed, fed, and housed me for eighteen years, and that abandoning them now was an act of profound spiritual betrayal.
I responded to none of them. I archived every voicemail, took high-resolution screenshots of every text, and uploaded them directly to the shared discovery folder I had established with David Vance.
By Thursday afternoon, the conflict breached my physical perimeter.
I was sitting in my living room reviewing code when three violent, unmetered thumps rattled my apartment door. I stood up, walked quietly down the short hallway, and looked through the glass peephole.
It was Rachel.
Her eyes were bloodshot, her mascara smeared across her cheekbones, her unwashed hair pulled back into a ragged knot. She was clutching a manila folder stuffed with unopened envelopes and utility notices.
“Mark!” she screamed, pounding her palms against the metal frame of the door. “Open the damn door! I know you’re in there! Open the door!”
I stood silently in the hallway, three inches of reinforced steel between us, my arms crossed over my chest. I did not move. I did not speak.
“My kids have no heat!” she shrieked, her voice cracking into a jagged, desperate register that echoed down the quiet apartment corridor. “They have no Wi-Fi! They can’t do their homework! The furniture company came back today with a repossession notice for the sectional and the beds! How can you do this to your own family? You selfish, miserable bastard! Fix this!”
She waited for twenty seconds, breathing heavily, listening for footsteps. When nothing answered her except the hollow hum of the building’s ventilation system, she dropped to her knees. A sheet of paper slid across the hardwood floor beneath the door gap.
It was the final financing statement from Interior Comforts Gallery. Across the top, scrawled in violent, bleeding red marker, were two words: FIX THIS.
I waited until her footsteps retreated down the fire stairs and the heavy security door clicked shut in the lobby.
I picked up the invoice, scanned it with my phone, emailed the document to David Vance, and then dropped the paper into the cross-cut shredder beside my desk.
Ten minutes later, I contacted Interior Comforts’ loss-prevention unit, provided the case number from my FTC fraud filing, and supplied the legal notice prepared by my attorney. I clarified that the delivery address was the sole beneficiary of the merchandise, that the authorization was fraudulent, and that any civil recovery should be directed exclusively to the occupants of Forty-Two Maple Crest Drive.
At 9:45 PM that evening, my email dinged with a message from an account I had not seen in months: my father’s personal address.
There was no subject line. There was only one sentence in the body:
You have made an enemy of your own blood. Good luck sleeping at night.
I looked at the words on the screen. For years, the threat of his disapproval had operated as an invisible electric fence, shocking me back into compliance whenever I dared to establish an independent boundary.
Now, reading his final curse in the quiet security of my home, I felt nothing. No panic. No sorrow. Only the vast, clean relief of an amputated limb that had long since gone gangrenous.
I went to bed at 10:30 PM and slept uninterrupted for eight hours.
A trapped predator does not surrender; it lashes out at whatever targets remain within reach.
The following Tuesday, I was summoned to a morning meeting with our Director of Human Resources and my department vice president. When I entered the glass-walled conference room, their expressions were not hostile, but intensely guarded.
“Mark, take a seat,” the HR director said gently, sliding a printed document across the table. “Late yesterday afternoon, our corporate ethics hotline received an anonymous, detailed report alleging that you have been utilizing company computational infrastructure and corporate credit instruments to facilitate private, fraudulent loan transactions.”
I picked up the document. The language was clumsily bureaucratic, masquerading as professional whistleblowing, but the underlying cadence was unmistakably my father’s: vague accusations of “financial impropriety,” claims that I was “under active investigation by state banking authorities,” and warnings that the company’s reputation was at catastrophic risk.
They had tried to destroy my livelihood.
They had tried to take the very engine that produced the money they coveted and smash it out of pure, spiteful malice.
I opened my leather portfolio and placed two documents on the table: the formal cease-and-desist letter drafted by David Vance, and the FTC Identity Theft Affidavit confirming that I was the victim of documented familial fraud.
“This is retaliation from my estranged father,” I said, my voice steady, measured, and completely devoid of emotion. “He forged my signature on several private loan documents that are currently undergoing institutional recovery. When I initiated fraud disputes with the respective lenders, he chose this avenue to pressure me. I have already retained legal counsel.”
The HR director read the affidavit, looked up at the VP, and let out a weary breath. “We figured it was something along these lines, Mark. The IP address of the hotline submission traced back to a consumer broadband account registered to a Jeffrey Miller. We will document this as an unfounded, malicious external inquiry and append this affidavit to your personnel file for your protection.”
When I left the office that afternoon, any lingering shred of nostalgia—any microscopic remnant of filial affection—had been eradicated.
That night, my lawyer served formal Cease and Desist directives via certified process server to Jeffrey Miller, Karen Miller, and Rachel Miller. Any further contact—direct, indirect, digital, or through third parties—would result in immediate petitions for civil protection orders and emergency injunctive relief.
At the same time, the institutional machine accelerated.
The mortgage lender’s forensic unit, having reviewed the fraudulent tax returns and fabricated co-signer signatures submitted during my parents’ last refinancing cycle, issued an immediate acceleration notice. The note was called due in full: $348,000 within thirty days, or the property would be transferred to the public trustee for foreclosure auction.
They had thirty days to produce a fortune they had never possessed.
The collapse concluded in the dead of winter.
In mid-January, my mother bypassed the cease-and-desist letter by the only method she had left: a handwritten letter sent via regular mail, addressed in her immaculate, looping blue cursive.
I sat at my kitchen table, turning the envelope over in my hands. The paper felt fragile, pathetic. I opened it with a butter knife and read the four pages inside.
It was an operatic masterpiece of emotional manipulation. She chronicled the misery of their new reality: how the furnace was running on an emergency space heater, how the neighbors were whispering about the foreclosure notices, how Rachel had been forced to move her three children into Aunt Mara’s basement, and how my father’s health was deteriorating under the unbearable stress.
And then, in the final paragraph, her mask slipped entirely:
“After everything we did for you—sacrificing our youth, giving you a roof over your head, putting food in your mouth when you were an ungrateful, difficult boy—you repay us by treating your own flesh and blood like criminals. You are a cold, heartless stranger. You should get down on your knees and thank God we ever let you be part of this family at all.”
I read that sentence twice: You should get down on your knees and thank God we ever let you be part of this family at all.
It was the ultimate truth of our relationship, laid bare on lined stationery. In their eyes, my existence was not a life to be nurtured, but a debt to be repaid. My inclusion in the family unit was a conditional lease, and the rent was total financial submission.
I did not burn the letter. I did not cry.
I took out my phone, photographed every page for David Vance’s harassment file, and placed the original paper into the rear divider of my metal file cabinet, filed alphabetically under Miller, Jeffrey & Karen: Evidence.
A week later, the local real estate legal notices published the public trustee’s foreclosure schedule. Forty-Two Maple Crest Drive was listed for immediate sheriff’s sale.
Rachel took to social media one final time, posting a sprawling, seventeen-paragraph screed about “sociopathic family members who choose money over innocent children.” But the digital community she sought validation from had begun to sour. Several extended cousins commented publicly, asking why she had never gotten a steady job to help pay the mortgage, and an uncle plainly asked: “Didn’t Jeff admit he forged Mark’s name on that truck loan?” Rachel deleted her profile within forty-eight hours.
The final communication came on a freezing Tuesday morning in late February.
It was a voicemail from a restricted number. I didn’t answer it, but the transcription populated on my screen:
“Mark… it’s your dad. I… we’re out. The bank took the keys this morning. Rachel’s gone to Mara’s. Your mother won’t speak to me. I’m staying at a residential motel off the interstate. I know you hate me. I get it now. I made mistakes. We made mistakes. But if there’s anything left… anything at all from when you were my boy… please call me. Just call me.”
His voice was hoarse, fractured, and old.
For a fraction of a second, an ancient, conditioned reflex twitched within my chest—the urge to reach out, to smooth the waters, to open my wallet and make the pain stop.
Then I remembered the anonymous call to my HR director. I remembered the fraudulent loans. I remembered the red marker scrawled across the furniture bill: FIX THIS.
I did not call back.
He had misdiagnosed the situation completely. I didn’t hate him. Hate requires emotional expenditure; it requires an active investment of rage and presence. What I felt was a complete, immovable absence. The cord had been severed, and the ship had sunk to the bottom of the ocean.
In April, I bought my first home.
It was a two-bedroom loft on the tenth floor of a converted industrial warehouse in downtown Denver. It had exposed brick walls, soaring twelve-foot concrete ceilings, polished timber floors, and floor-to-ceiling windows that looked out directly over the snow-capped expanse of the Rocky Mountains.
I bought it entirely under my own name, using my restored, spotless credit score and the savings that accumulated with shocking velocity once the invisible parasites had been eradicated from my accounts.
I furnished it slowly, intentionally. I bought a low-profile Italian leather sofa, a solid walnut dining table, and a pair of mid-century reading chairs. Every piece was paid for in full at the time of delivery. Every receipt bore my name alone.
On a warm evening in late May, I stood on my balcony with a glass of rye whiskey, watching the sun dip behind the mountains, casting long, violet shadows across the Denver skyline.
Down on the street below, the traffic moved in an endless, rhythmic hum—thousands of people moving toward their homes, their obligations, their families.
For decades, I had believed that love was a transaction—that my value as a human being was inextricably tied to how much pain I could absorb on behalf of people who would never thank me for it. I had believed that being the “responsible one” meant keeping everyone else afloat, even if it meant drowning myself in the process.
I took a slow sip of the whiskey. Behind me, the loft was quiet, peaceful, and clean.
There were no envelopes slid beneath the door. There were no unauthorized alerts flashing across my phone. There was no one waiting in the shadows to explain why my success belonged to them.
I set my glass down on the iron railing, turned around, and walked back inside, closing the heavy, soundproof glass door behind me. I turned the deadbolt until it clicked.
It was a quiet sound—barely louder than a whisper. But it was the sound of a door that no one else had a key to.
Not my father. Not my mother. Not my sister.
No one.
And in that profound, unyielding silence, I was finally home.